

Divorce
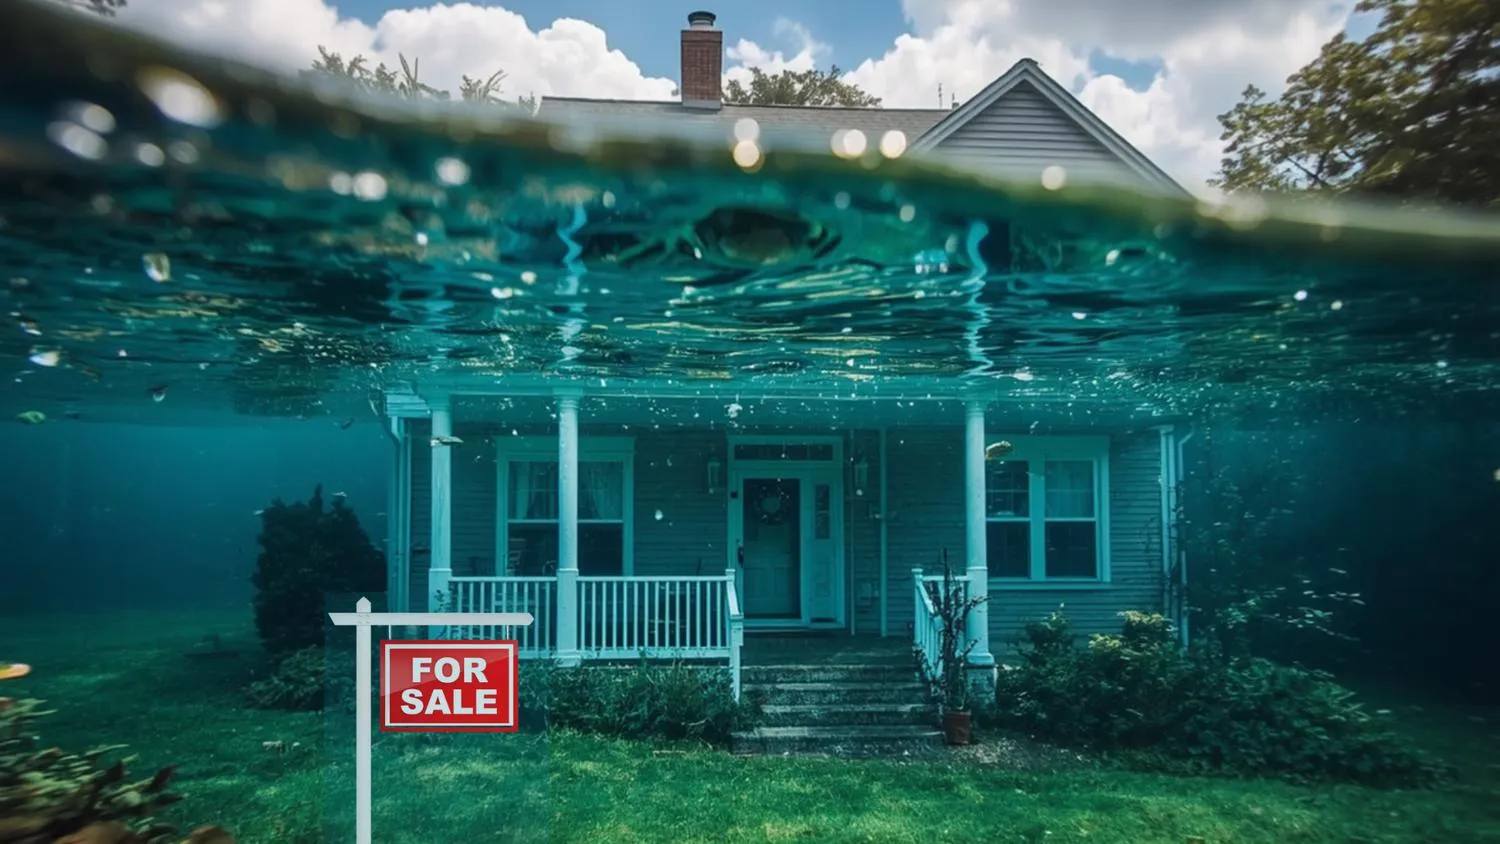
What Happens If You Owe More Than Your House Is Worth During a Divorce in Texas?
Going through a divorce is already stressful.
But if you also find out that you owe more on your house than it’s worth, it can feel like everything just got a lot more complicated.
If you’re in Houston or the surrounding areas, you might be asking:
“What do we do if we can’t sell the house for what we owe?”
This situation is more common than people think—and while it may feel overwhelming, you do have options.
Let’s walk through what this really means and what you can do next.
First, What Does “Owing More Than It’s Worth” Mean?
This is often called being “underwater” on your mortgage.
It simply means:
👉 The amount you owe on your loan is higher than what your home would likely sell for today
So if your mortgage balance is $350,000, but your home might sell for $320,000, there’s a gap.
And during a divorce, that gap becomes something you have to deal with together.
Why This Feels So Difficult During a Divorce
In a normal situation, you might choose to wait and let the market improve.
But during a divorce, waiting isn’t always realistic.
You’re trying to:
- separate finances
- move forward
- reduce shared responsibilities
And the house becomes one of the biggest pieces of that puzzle.
If you’re already dealing with mortgage questions, this guide explains 👉 what happens to a mortgage during a divorce in Texas and why both parties may still be financially tied to it.
Your Real Options (In Plain English)
Even in this situation, there are still a few paths forward.
None of them are perfect—but one will usually make the most sense for your situation.
Option 1: Sell and Cover the Difference
In some cases, couples choose to sell the home and bring money to closing to cover the gap.
This allows you to:
- pay off the mortgage
- fully separate financially
- move forward cleanly
But this option depends on whether both parties have the ability to cover that difference.
Option 2: Wait and Hold the Property
Some couples choose to keep the home for a period of time and wait for the market to improve.
This can work if:
- both parties can afford the payments
- there is cooperation
- there’s a clear short-term plan
But it also means staying financially connected longer.
Option 3: Explore a Short Sale
In certain situations, a short sale may be an option.
This is when the lender agrees to let the home be sold for less than what is owed.
It’s not always simple, and it does require lender approval—but for some homeowners, it creates a path forward when selling normally isn’t possible.
What We Would Do in This Situation
If you’re in this situation—owing more on your home than it’s worth during a divorce—the first step is to slow things down and get clear on the numbers.
We would start by looking at what your home could realistically sell for in today’s Houston market, not just an estimate online. Then we’d compare that to your current mortgage balance so you can clearly see what the gap actually looks like.
From there, we’d walk you through your options in a straightforward way.
That might mean looking at what it would take to sell and cover the difference, exploring whether holding the property for a period of time makes sense, or discussing what a short sale could look like in your specific situation.
The goal isn’t to push you into one direction—it’s to help you understand what each path really means for you financially and practically.
Because once you have that clarity, the situation usually feels a lot less overwhelming.
And from there, you can make a decision that helps you move forward—without dragging things out or creating more stress than necessary.
What Most People Don’t Realize
The hardest part of this situation isn’t always the numbers.
It’s the uncertainty.
When you don’t know your options, everything feels heavier.
But once you understand what’s actually possible, you can start making decisions that move you forward.
How This Connects to the Bigger Decision
In many cases, this situation ties directly into a bigger question:
👉 Should you sell… or should one person keep the home?
If you’re trying to work through that decision, this guide on 👉 should you sell or buy out your spouse in a divorce in Texas can help you see the full picture.
The Biggest Mistake to Avoid
The biggest mistake is ignoring the situation or hoping it will fix itself.
Delays can lead to:
- continued financial pressure
- missed opportunities
- more stress over time
Clarity first… then action.
Next Steps
If you’re going through a divorce and dealing with a home that’s worth less than what you owe, the most important step is understanding your options clearly.
The Move Live Love TX Team™, based in The Woodlands, helps homeowners across Houston and surrounding areas navigate situations like this with a plan—not guesswork.
If you need help understanding your home’s value, your options, and what makes the most sense for your situation, we’re here to help guide you so you can move forward with confidence.
Frequently Asked Questions
- What happens if you owe more than your house is worth during a Texas divorce?
- Being 'underwater' on a mortgage during divorce means the couple has to deal with the gap together, typically through selling and covering the difference, holding the property, or exploring a short sale.
- Can a couple sell an underwater home during divorce?
- Yes — some couples bring money to closing to cover the gap between the sale price and mortgage balance, allowing them to fully separate financially.
- What is a short sale and when might it apply during a Texas divorce?
- A short sale is when the lender agrees to let the home sell for less than what is owed — it requires lender approval and isn't simple, but it can create a path forward when selling normally isn't possible.
- Is holding onto an underwater home during divorce a good option?
- It can work if both parties can afford the payments and there's cooperation and a clear short-term plan, but it means staying financially connected longer.
- What's the biggest mistake with an underwater home during a Texas divorce?
- Ignoring the situation or hoping it fixes itself, which can lead to continued financial pressure and more stress over time.