

Veterans
How Do You Get Pre-Approved for a VA Loan in Houston?
To get pre-approved for a VA loan in Houston, you give a VA-approved lender your income, credit and military service documents, and they review them and give you a written letter showing how much you can borrow. It usually takes a few days to about a week once your paperwork is ready, and it comes before you start touring homes.
Here is what the process involves, what you need to have ready, and what affects the amount you’re approved for.
The Move Live Love TX Team™ is a Houston, Texas real estate team based in The Woodlands. We help veteran buyers get started the right way — starting with a pre-approval process that actually sets them up for success.
Before anything else
Pre-approval is a lender’s written assessment of how much you can borrow based on a review of your income, credit, debts, and military service. It’s different from pre-qualification, which is a quick, informal estimate based on information you self-report without any verification.
Pre-qualification takes a few minutes and tells you roughly where you stand. Pre-approval takes documentation, a credit pull, and a real underwriting review — and it results in a letter you can actually use when you make an offer.
In Houston’s market, a pre-qualification letter doesn’t carry much weight with sellers. A pre-approval letter does. That difference matters more than most first-time buyers realize.
What you’ll need to provide
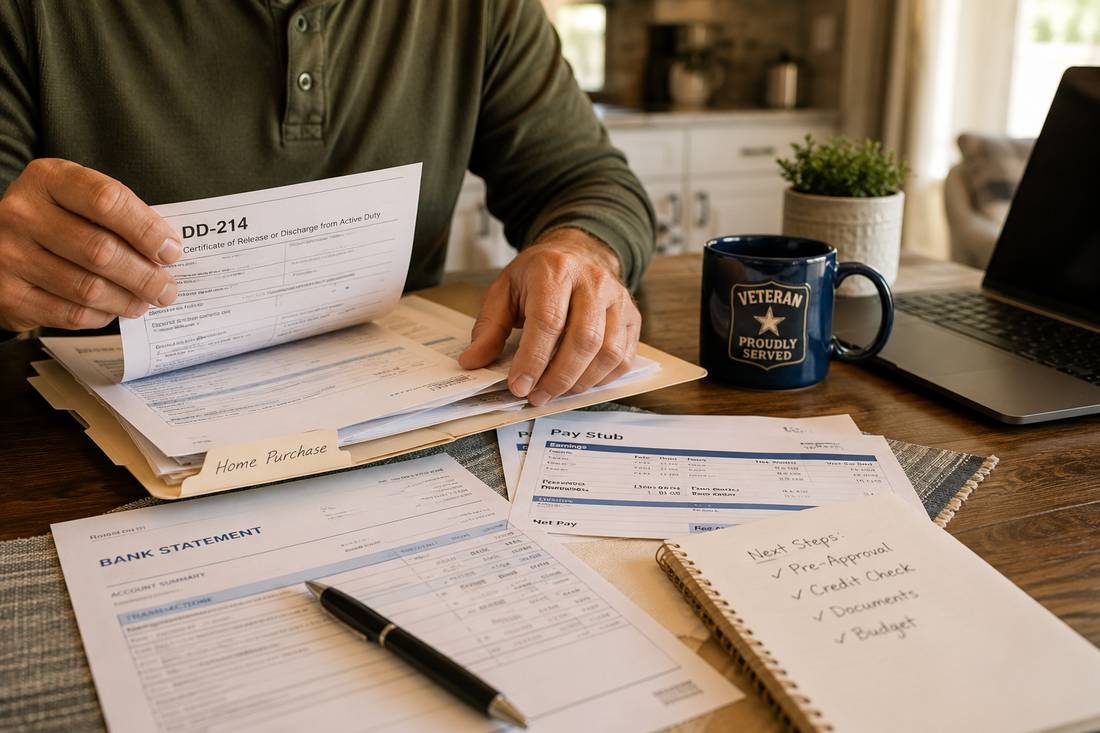
Your lender will ask for documentation to verify your income, your credit, your military service, and your overall financial picture. Here’s what to have ready before you start the process.
For income verification, you’ll need recent pay stubs, your last two years of W-2s or tax returns, and documentation of any additional income like BAH, disability compensation, or retirement pay. If you’re self-employed, expect to provide two years of business tax returns and possibly a profit and loss statement.
For military service, you’ll need your DD-214 if you’ve separated, or a current Statement of Service if you’re still active duty. Your lender will also pull your Certificate of Eligibility, which confirms your VA entitlement.
For credit, your lender will run a credit check as part of the process. You don’t need to provide anything for this beyond authorization — they pull it directly.
For assets, expect to provide two to three months of bank statements showing your savings and checking account balances. Even though VA loans don’t require a down payment, lenders want to see that you have reserves to cover closing costs and a financial cushion.
How long pre-approval takes
In most cases, pre-approval can be completed in a few days to about a week, assuming you have your documentation ready and respond quickly to any follow-up requests.
The biggest factor in how fast this moves is you. Lenders can typically process a complete file fast. What slows things down is waiting on documents, tracking down old tax returns, or not responding to requests for clarification.
If you’re planning to start house hunting in Houston soon, getting your documents together before you contact a lender saves real time. We covered the documents worth having ready in more detail in how long does it take to close on a VA loan in Houston, which walks through the full closing timeline beyond just pre-approval.
What affects how much you’re pre-approved for
A few things determine your pre-approval amount, and understanding them helps you know what to expect before you even apply.
Your income is the foundation — both the amount and the stability of it. Lenders want to see consistent income over at least two years, though exceptions exist for certain situations like a recent transition out of active duty.
Your debt-to-income ratio matters significantly. This is the percentage of your gross monthly income that goes toward debt payments, including your future mortgage payment. VA guidelines are more flexible here than conventional loans, but lenders still factor it heavily into your approval amount.
Your residual income — what’s left over each month after major expenses — is a VA-specific factor that can work in your favor even if your debt-to-income ratio looks tight on paper. This is one of the real advantages of VA underwriting.
And your entitlement, if you’ve used a VA loan before, can affect your approval amount depending on how much remaining entitlement you have. For the full breakdown on how entitlement works, VA loan limits and entitlement explained for Houston buyers covers that in detail.
Pre-approval and your credit
Your credit profile plays a real role in pre-approval, but VA underwriting evaluates it differently than conventional financing. If your credit has some rough spots, that doesn’t automatically mean pre-approval is out of reach.
We’ve written a full breakdown of how VA lenders evaluate credit-challenged buyers in can a veteran buy a home in Houston with bad credit, including what compensating factors can help and what waiting periods apply after a bankruptcy or foreclosure.
What happens after you’re pre-approved
Once you have your pre-approval letter, it’s typically valid for 60 to 90 days, though this varies by lender. If your home search takes longer than that, your lender can usually update or refresh it without starting the process over from scratch.
During this window, avoid opening new credit accounts, making large purchases, or changing jobs if you can help it. Any of these can affect your approval and create complications right when you’re trying to make an offer. Lenders re-verify key details before closing, and changes during the pre-approval window are one of the more common reasons a deal hits a snag late in the process.
Your pre-approval letter is also the thing that gets attached to every offer you make. Choosing the right lender before you get this letter matters — a strong pre-approval from a respected VA lender makes your offer more competitive in Houston’s market. We covered what to look for in a lender in how to choose a VA lender in Houston.
What we would do
If a veteran reached out to us before they’d talked to a lender, the first thing we’d do is connect them with a VA-specialized lender we trust — not just anyone offering VA loans, but someone with real volume and experience.
Then we’d walk them through exactly what documentation to gather before the conversation even starts, so the process moves as fast as possible once it begins.
And once they have their pre-approval letter in hand, that’s when the real house hunting starts — with a clear number, a strong letter, and confidence about what they can actually afford.
Vicky Royster holds the Military Relocation Professional (MRP) designation, specialized training in helping military families and veterans get started the right way from the very first pre-approval conversation.
The bottom line
Pre-approval isn’t just a box to check before you start looking at homes. It’s the foundation that makes everything after it move faster and with more confidence — from the strength of your offer to your peace of mind walking into a negotiation.
Get your documents together, choose the right lender, and get pre-approved before you fall in love with a house. It puts you in the strongest possible position from day one.
For the full picture of buying a home in Houston with your VA benefits, visit Everything a Veteran Needs to Buy a Home in Houston or download the VA Home Buying Guide.
Vicky Royster holds the Military Relocation Professional (MRP) designation, specialized training in helping military families and veterans navigate home buying and relocation.
Frequently Asked Questions
- What's the difference between VA loan pre-qualification and pre-approval?
- Pre-qualification is a quick, informal estimate based on self-reported information, while pre-approval involves documentation, a credit pull, and a real underwriting review resulting in a usable letter.
- What documents does a veteran need for VA loan pre-approval?
- Recent pay stubs, two years of W-2s or tax returns, a DD-214 or Statement of Service, and two to three months of bank statements showing reserves.
- How long does VA loan pre-approval take in Houston?
- Typically a few days to about a week, assuming documentation is ready and follow-up requests get quick responses.
- What is residual income and why does it matter for VA pre-approval?
- It's what's left over each month after major expenses — a VA-specific factor that can work in a buyer's favor even if their debt-to-income ratio looks tight on paper.
- How long is a VA pre-approval letter valid?
- Typically 60 to 90 days depending on the lender, though it can usually be refreshed without restarting the whole process if the home search takes longer.